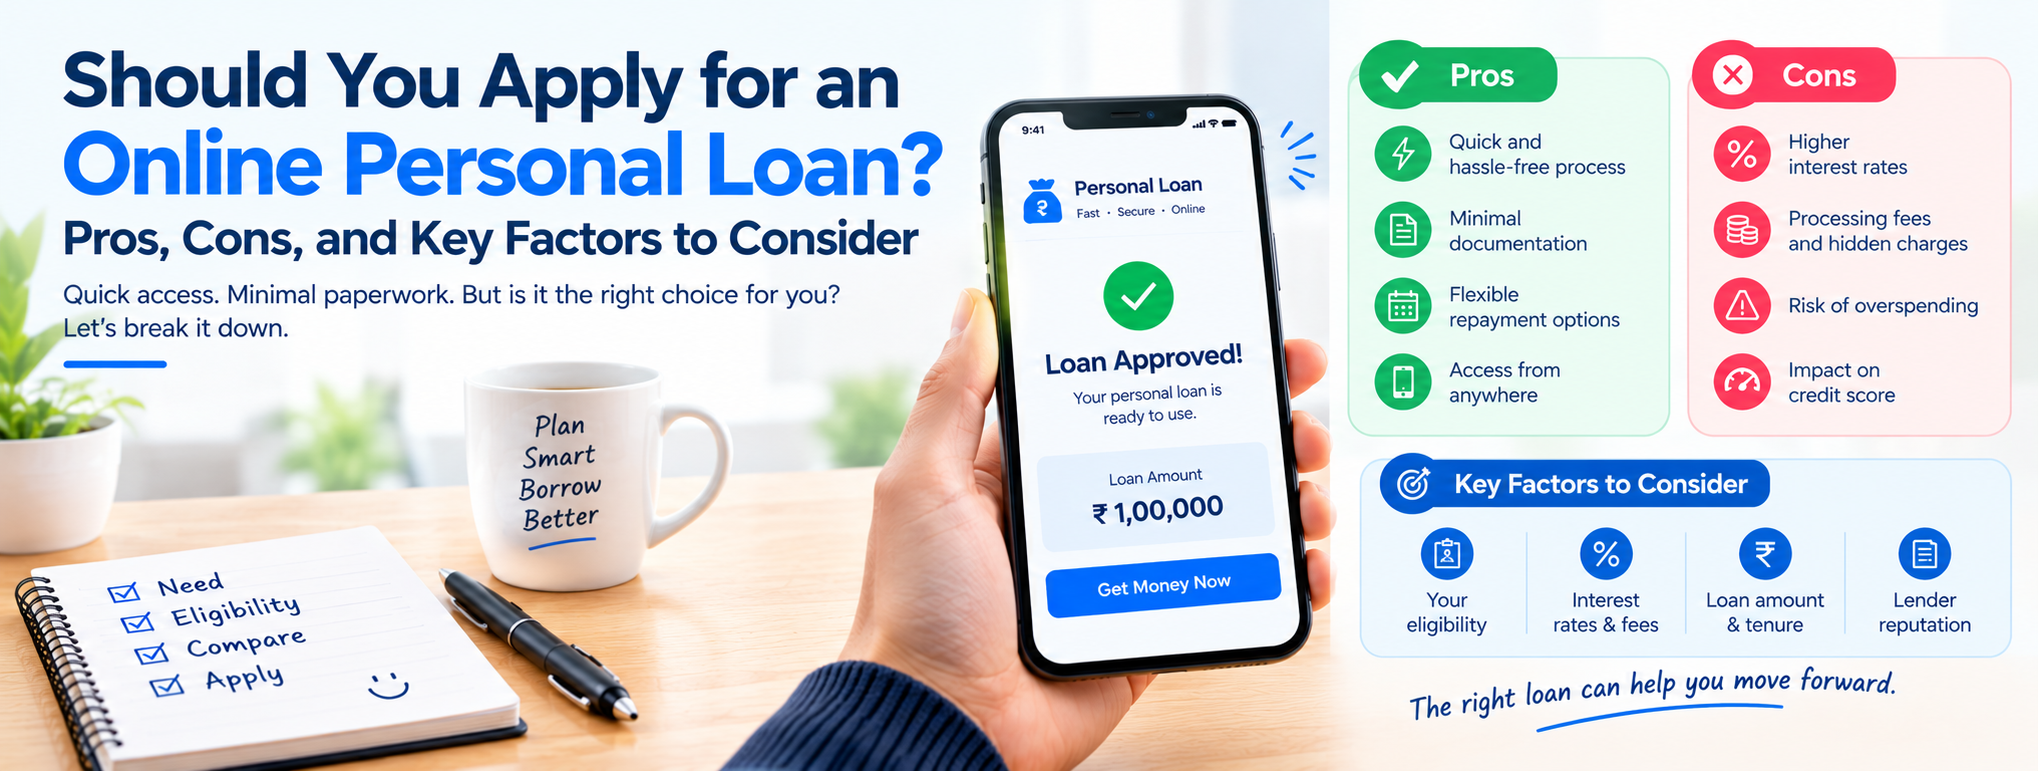
Thinking about an online personal loan? Explore real pros, cons, interest rates, eligibility & documents needed before you apply. Read FixRupee's expert guide.
Introduction
It's the last week of the month. Your car has broken down, a medical bill just landed in your inbox, or your child's school fee is due, and your salary account isn't cooperating. Sound familiar? This is exactly the kind of moment when most people in Bangalore, and across India, start typing "online personal loan" into Google at 11 PM.
An online personal loan promises quick funds, minimal paperwork, and no need to visit a branch. But is it actually the right move for your situation, or could it create more financial stress than it solves?
This guide breaks down everything you need to know, the real benefits, the genuine drawbacks, how the process works, and the factors that decide whether an online personal loan is a smart choice or a costly mistake. By the end, you'll know exactly how to decide, and how to apply for a personal loan online the right way.
What Is an Online Personal Loan?
An online personal loan is an unsecured loan you can apply for, get approved, and receive entirely through a website or mobile app, no branch visit, no physical paperwork, no long queues.
Because it's a personal loan without collateral, lenders base their decision mainly on your income, credit score, and repayment history rather than any asset you pledge. Banks, NBFCs, and digital lending platforms all now offer this route, and in cities like Bangalore, home to a huge working professional and startup population, digital personal loans have become the default way people borrow for short-term needs.
In short: it's the same personal loan your parents' generation applied for at a bank counter, just digitized from start to finish.
How Online Personal Loans Work: Step-by-Step
Understanding how online personal loans work removes a lot of the confusion (and hesitation) around applying. Here's the typical journey:
- Check eligibility, Most lenders let you check personal loan eligibility instantly using your PAN, income, and credit score, without affecting your credit report.
- Fill the online application, Basic details: income, employment type, loan amount, and tenure.
- Upload documents digitally, ID proof, address proof, income proof, and bank statements are uploaded as scanned copies or PDFs.
- e-KYC verification, Aadhaar-based e-KYC confirms your identity in minutes instead of days.
- Credit and income assessment, The lender's system evaluates your CIBIL score, repayment capacity, and existing obligations.
- Loan approval and offer, You receive the approved amount, applicable personal loan interest rates, tenure options, and processing fees.
- e-Sign the agreement, Digital signature replaces physical paperwork.
- Disbursal Funds are credited directly to your bank account, often within hours.
If you want a deeper look at how EMIs are calculated at each stage, FixRupee's personal loan EMI calculator guide walks you through the exact numbers so there are no surprises later.
Should I Take an Online Personal Loan? Ask Yourself This First
Before comparing pros and cons, ask three honest questions:
- Is this expense necessary and time-sensitive? (Medical emergency, urgent repair, essential purchase, yes. Discretionary spending you can delay, think twice.)
- Can I comfortably afford the EMI without straining my monthly budget?
- Do I have a repayment plan that survives an unexpected dip in income?
If you answered yes to all three, an online personal loan can be a genuinely useful financial tool. If not, it's worth exploring alternatives first, even a smaller short-term loan or a quick top-up from savings might serve you better than a larger, longer commitment.
Pros of an Online Personal Loan
1. Speed and Convenience
This is the single biggest reason online personal loan benefits outweigh the old branch-visit model for most urban borrowers. There's no need to take time off work, stand in a queue, or coordinate with a bank representative. The entire process, from application to disbursal, can be completed from your phone.
For working professionals in Bangalore juggling long commutes and demanding jobs, this convenience alone often decides the choice between a bank loan and a quick personal loan online.
2. Fast Approval and Disbursal
Traditional loan approval could take anywhere from 3 to 10 working days. Digital lenders, using automated underwriting and e-KYC, can approve and disburse an instant personal loan online within a few hours, sometimes minutes for pre-approved customers.
This makes online personal loans ideal for genuine emergencies: hospital bills, urgent repairs, or a sudden shortfall that can't wait a week.
3. Minimal Documentation
Because most of the personal loan documents required, PAN, Aadhaar, salary slips, bank statements, can be uploaded digitally, there's no need to photocopy files or carry originals to a branch. Many lenders also pull your bank statement digitally via account aggregator frameworks, cutting the process down even further.
4. No Collateral Required
A personal loan without collateral means you don't have to pledge property, gold, or fixed deposits. Your loan is approved purely on your income and creditworthiness. This makes it accessible to salaried professionals and self-employed individuals who may not have assets to pledge but have a steady income.
5. Transparent Comparison of Rates and Fees
Online platforms typically display personal loan interest rates, personal loan processing fees, and personal loan repayment terms upfront, often with an EMI calculator built in, so you can compare offers from multiple lenders before committing. This transparency was much harder to get when loans were sold primarily through in-branch conversations.
6. Flexible Use of Funds
Unlike a home loan or vehicle loan, personal loans are rarely end-use restricted. Whether it's a wedding, travel, medical expense, debt consolidation, or a home renovation, the funds are yours to use as needed.
7. Builds and Diversifies Your Credit Profile
Timely personal loan repayment, through EMIs paid on schedule, helps build a stronger credit history over time, which can improve your eligibility for larger loans (like a home loan) later. If your score isn't strong yet, FixRupee's guide on getting a personal loan with a low credit score explains practical ways to still get approved.
Cons of an Online Personal Loan
No borrowing decision is one-sided. Here are the genuine online personal loan disadvantages to weigh carefully.
1. Interest Rates Can Be Higher Than Secured Loans
Since there's no collateral backing the loan, lenders price in more risk. Personal loan interest rates are typically higher than home loans or loans against property. If you don't compare offers, you could end up paying significantly more over the loan tenure.
2. Processing Fees and Hidden Charges
Personal loan processing fees, prepayment penalties, late payment charges, and GST on charges can add up. Always ask for the complete break-up before signing, a loan that looks cheap on the surface can carry costs buried in the fine print.
3. Risk of Overborrowing
Because approval is fast and the process is frictionless, it's easy to borrow more than you actually need, or take a loan for a want rather than a need. This is one of the most overlooked online personal loan disadvantages, and it's purely behavioural, not structural.
4. Impact on Credit Score if Mismanaged
Missed or delayed EMIs can hurt your CIBIL score, making future borrowing harder and more expensive. If you're already managing a tight budget, check FixRupee's explainer on the minimum CIBIL score required for a personal loan before applying, so you know where you stand.
5. Fraudulent Lending Apps
The convenience of digital lending has unfortunately also attracted unregulated apps that mimic legitimate lenders. Always verify that a lending platform is backed by an RBI-registered NBFC or bank before sharing personal or financial documents.
6. Prepayment and Foreclosure Charges
Some lenders charge a fee if you want to repay your loan early. If you expect a bonus, increment, or lump sum that could help you close the loan sooner, check these terms in advance.
Online Personal Loan Pros and Cons: Quick Comparison
| Factor | Pros | Cons |
|---|---|---|
| Speed | Approval and disbursal within hours | Encourages impulsive borrowing |
| Documentation | Fully digital, minimal paperwork | Still requires accurate income proof |
| Collateral | None needed | Higher interest rate as trade-off |
| Access | Available to salaried & self-employed | Riskier for low or irregular income |
| Cost | Transparent comparison tools online | Processing fees & charges can add up |
| Credit Impact | Builds credit history if repaid on time | Damages score if EMIs are missed |
Key Factors to Consider Before Applying
Personal Loan Eligibility
Most lenders assess personal loan eligibility based on:
- Age, typically 21 to 60 years
- Income, minimum monthly income varies by lender and city (often ₹15,000–₹25,000 in metro cities like Bangalore)
- Employment type, salaried, self-employed professional, or business owner
- Credit score, generally 700+ improves your chances of approval and better rates
- Existing obligations, your current EMIs and debt-to-income ratio
Personal Loan Interest Rates
Rates vary based on your credit profile, income stability, and the lender's risk assessment. A strong CIBIL score, low existing debt, and stable employment history typically unlock lower rates. Always compare the annual percentage rate (APR), not just the headline interest rate, since APR includes processing fees and other charges.
Personal Loan Processing Fees
These usually range from 1% to 3% of the loan amount, though they vary by lender. Factor this into your total cost of borrowing, not just the EMI.
Personal Loan Repayment Terms
Tenures typically range from 12 to 60 months. A longer tenure lowers your EMI but increases total interest paid; a shorter tenure does the opposite. Use an EMI calculator to model different scenarios, FixRupee's EMI calculator guide is a good starting point to understand how tenure and rate together affect your monthly outgo.
Personal Loan Documents Required
Standard documents typically include:
- PAN card
- Aadhaar card (for e-KYC)
- Latest salary slips (usually last 3 months)
- Bank statements (usually last 3–6 months)
- Photograph
- Business proof (for self-employed applicants)
Personal Loan Approval Timeline
While marketing often promises instant approval, actual disbursal timelines depend on how quickly you complete e-KYC, how clean your credit report is, and how thoroughly you've filled out the application. Incomplete or inconsistent details are the most common reason for delays.
How to Apply for a Personal Loan Online: A Simple Checklist
If you've decided an online personal loan is the right fit, here's how to apply for a personal loan online without hiccups:
- Check your credit score first, know where you stand before applying.
- Compare at least 3 lenders on interest rate, processing fee, and tenure flexibility.
- Use an EMI calculator to pick a repayment amount that fits your budget comfortably.
- Keep documents ready in digital format (scanned or clear photos).
- Read the loan agreement fully before e-signing, especially charges and foreclosure terms.
- Set up auto-debit for EMI payments to avoid missed due dates.
If your situation is urgent, FixRupee's guide on getting a cash loan online quickly covers ways to speed up approval without cutting corners on due diligence.
Real-World Example
Consider Ravi, a 29-year-old software professional in Bangalore. His father was hospitalised, and the treatment cost ₹1.5 lakh more than his health insurance covered. Instead of borrowing from friends or liquidating a fixed deposit meant for a house down payment, he applied for an online personal loan through a digital platform. With a CIBIL score of 740, he was approved within four hours, and the funds reached his account the same evening.
He chose a 24-month tenure to keep the EMI manageable alongside his existing expenses, and set up auto-debit to avoid missing a due date. This is a textbook example of when an online personal loan works in your favour: a genuine, time-sensitive need, a manageable EMI, and a clear repayment plan.
Compare this to someone taking a similar loan for discretionary spending without checking their monthly budget, the outcome, and the stress it creates, would look very different.
The Rise of Digital Lending in India
Digital lending has grown rapidly in India over the past few years, driven by smartphone penetration, UPI adoption, and RBI-backed frameworks like Account Aggregator and e-KYC that make paperless verification possible. Bangalore, as one of India's largest hubs for salaried professionals and tech workers, has seen especially strong demand for digital personal loans, a reflection of a workforce that values speed and prefers managing finances from a phone rather than a branch.
This shift has also pushed lenders to compete more aggressively on transparency: clearer disclosure of personal loan interest rates, processing fees, and foreclosure terms than was common a decade ago. That's good news for borrowers, but it also means the responsibility to compare offers carefully now sits more with you, the applicant, than with a single bank relationship manager guiding you through one product.
At the same time, the RBI has tightened oversight of digital lending apps to protect borrowers from predatory practices, including mandates around transparent fee disclosure and restrictions on data access permissions. Understanding this backdrop helps explain both why online personal loans have become so convenient, and why due diligence on the lender still matters as much as ever.
Online Personal Loan vs Other Borrowing Options
- Credit card, Good for very short-term, smaller amounts, but revolving credit at high interest can spiral if not paid in full monthly.
- Gold loan, Lower interest since it's secured, but requires you to pledge gold, which not everyone has or wants to risk.
- Loan against fixed deposit, Cheaper interest but breaks or pledges your savings.
- Personal loan online, No collateral, flexible use, but typically higher interest than secured options.
The right choice depends on how quickly you need funds, whether you have assets to pledge, and how comfortable you are with the associated interest rate.
Things to Consider Before Taking a Personal Loan
Before you hit "Apply," run through this final checklist of things to consider before taking a personal loan:
- Does the EMI fit within 40–50% of your monthly take-home income (including existing debts)?
- Have you compared personal loan interest rates and processing fees across at least three lenders?
- Is the lender RBI-registered or affiliated with a regulated bank/NBFC?
- Do you understand the prepayment and foreclosure charges?
- Is there a genuine, time-bound need, or can this wait until you've saved enough?
- Have you checked your credit report for errors that could affect your rate?
If your income is currently irregular or you're worried about approval odds, it may also help to explore a short-term loan option in India designed for smaller, quicker needs rather than committing to a longer personal loan tenure.
Conclusion: So, Should You Apply for an Online Personal Loan?
An online personal loan is neither universally good nor bad, it's a financial tool, and like any tool, its value depends on how and why you use it. For genuine, time-sensitive needs with a clear repayment plan, it offers real advantages: speed, convenience, no collateral, and full transparency on rates and terms. But if taken impulsively, without comparing lenders or checking your repayment capacity, the same convenience can become a costly burden.
Before you apply, check your personal loan eligibility, compare personal loan interest rates and processing fees, and use an EMI calculator to make sure the repayment fits comfortably into your monthly budget.
Ready to see what you qualify for? Check your personal loan eligibility and apply online with FixRupee →
Frequently Asked Questions (FAQs)
1. Is it safe to apply for a personal loan online?
Yes, as long as you apply through an RBI-registered bank or NBFC, or a lending platform partnered with one. Always verify the lender's credentials, read the loan agreement carefully, and avoid apps that ask for excessive personal permissions on your phone.
2. How fast can I get an online personal loan approved?
Approval can take anywhere from a few minutes to a few hours for pre-qualified applicants with a clean credit history, and up to 1–2 business days if additional verification is needed. Disbursal typically follows within hours of approval.
3. What credit score do I need for an online personal loan?
Most lenders prefer a CIBIL score of 700 or above for the best interest rates, though approval is sometimes possible with a lower score, often with higher interest or a smaller loan amount. Read our guide on the minimum CIBIL score for a personal loan for specifics.
4. Can I get a personal loan without collateral?
Yes. Personal loans are unsecured by design, you don't need to pledge property, gold, or fixed deposits. Approval is based on income, credit score, and repayment capacity instead.
5. What documents are required for an online personal loan?
Typically PAN card, Aadhaar card, salary slips or income proof, and bank statements from the last 3–6 months. Self-employed applicants may need to submit business proof and ITR documents as well.
6. What happens if I miss an EMI payment on my personal loan?
Missing an EMI usually attracts a late payment fee and negatively impacts your CIBIL score, which can make future borrowing harder and more expensive. If you anticipate a delay, contact your lender proactively to discuss options rather than missing the payment silently.
Take the next step: Whether you need funds for an emergency, a big purchase, or to consolidate debt, apply for your personal loan online with FixRupee and get a clear picture of your eligibility, interest rate, and EMI, all in a few minutes.