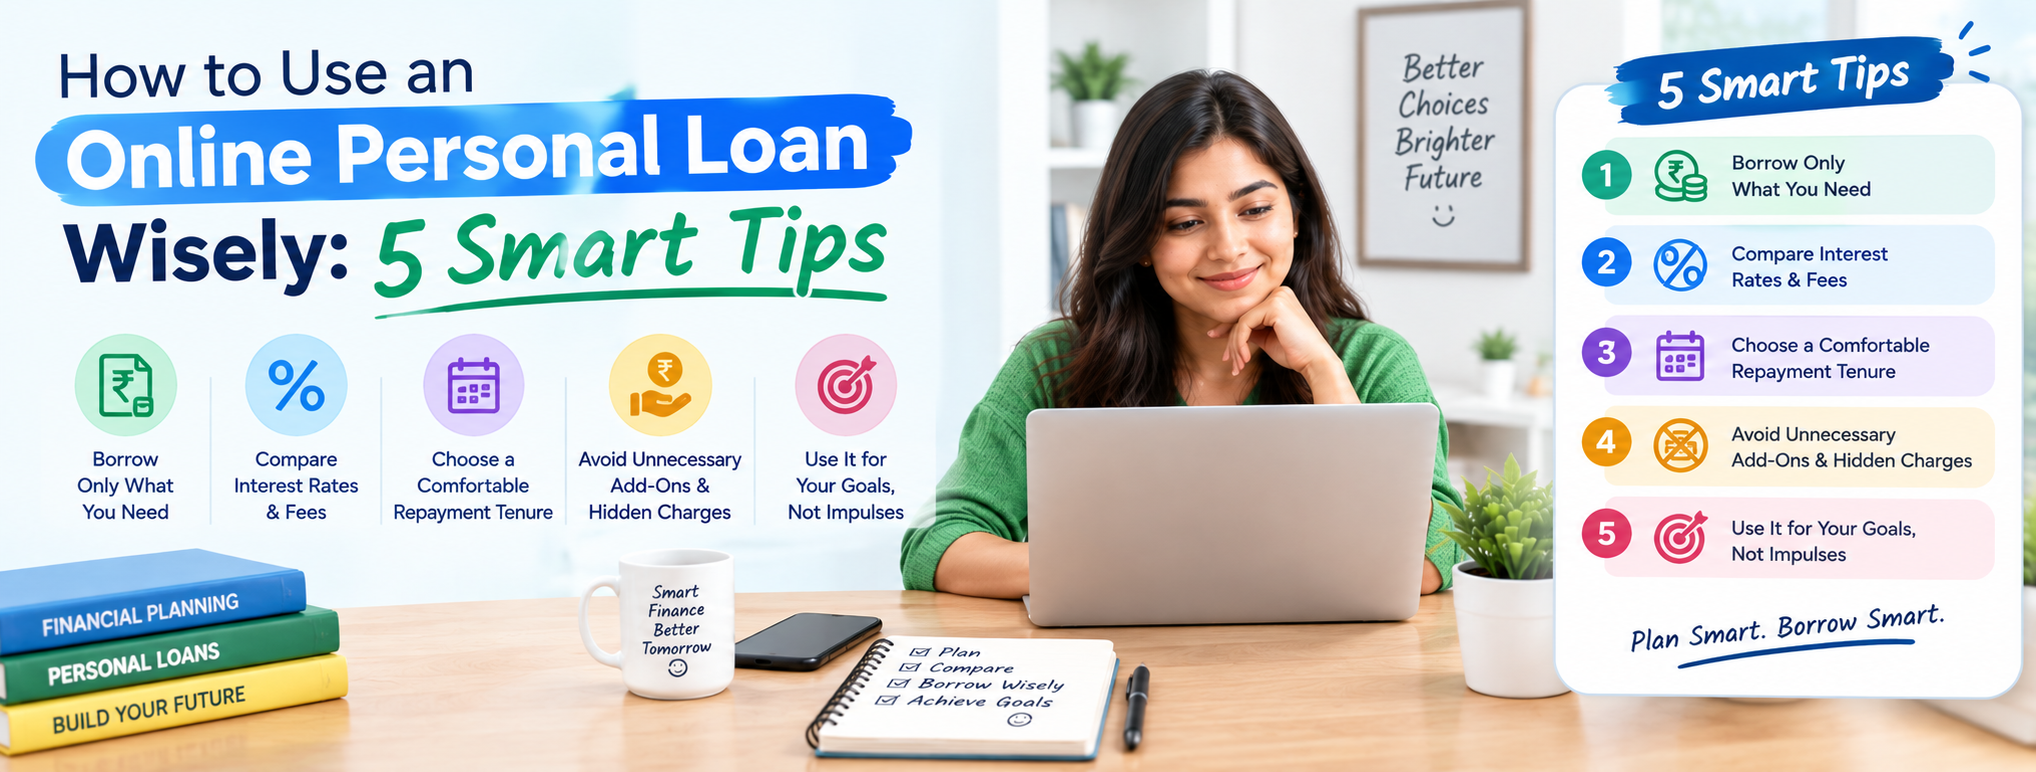
Learn how to use an online personal loan wisely with 5 smart tips on rates, EMIs, fees and faster repayment. Compare offers and apply with FixRupee today.
Introduction
You open your banking app on the 28th, and the balance looks thin. A medical bill has arrived, your landlord in Bangalore wants a revised rent, and the kitchen renovation you planned has stalled. Sound familiar? Millions of Indians face a cash crunch like this every year, and many turn to credit. The real question is not whether to borrow. It is how to use an online personal loan wisely so the loan solves a problem instead of creating a bigger one.
An online personal loan is fast, paperless and flexible. You can apply from your phone, upload documents in minutes and sometimes receive funds the same day. But speed can tempt people to borrow more than they need, ignore hidden charges or pick an EMI they cannot sustain.
This guide gives you five smart, practical tips, written in simple language and based on how lending actually works in India. You will learn how to pick the right purpose, calculate the right amount, compare offers, choose the best tenure and repay faster. Along the way, you will find answers to common questions, mistakes to avoid and links to deeper guides from our personal loan cluster.
To use an online personal loan wisely, borrow only for a clear need, check your eligibility and EMI before applying, compare interest rates and fees across lenders, pick a tenure you can comfortably afford, and repay on time or early to build your credit score.
What Is an Online Personal Loan?
An online personal loan is an unsecured loan you apply for and receive digitally, without visiting a branch or pledging collateral such as gold or property. You fill in an online loan application, complete KYC with Aadhaar and PAN, share income proof, and the lender checks your credit profile. If approved, the money lands in your bank account, often within 24 to 48 hours. Some lenders offer an instant personal loan online with disbursal in a few hours.
Because there is no security, lenders decide based on your income, employment stability and credit history. That is why interest rates are higher than for home or gold loans, and why careful use matters.
Benefits of Online Personal Loans
The benefits of online personal loans go beyond convenience:
- Speed: Digital KYC and automated checks cut approval time from days to hours.
- No collateral: You do not risk your home, car or gold.
- Flexible use: Funds can go towards medical bills, travel, weddings, education or renovation, subject to the lender's terms.
- Transparent comparison: You can view rates, fees and EMIs side by side before committing.
- Predictable repayment: Fixed EMIs make monthly budgeting easier.
- Credit building: On-time EMIs can strengthen your credit history.
If you want to weigh both sides before applying, read our guide on whether you should apply for an online personal loan: pros and cons.
Why Using a Personal Loan Wisely Matters
A personal loan is a tool. Like any tool, it helps when used for the right job and hurts when misused.
Consider the numbers. A loan of ₹3,00,000 at 14% for 36 months carries an EMI of roughly ₹10,250 and total interest of about ₹69,000. That is real money you pay for the convenience. If the loan funded a medical emergency or cleared 36% credit card debt, the trade-off makes sense. If it funded a luxury gadget you could have saved for, it does not.
Industry data from credit bureaus has shown, for several years running, that unsecured retail credit, including personal loans and credit cards, is one of the fastest growing segments of lending in India. The RBI has repeatedly flagged the need for prudent borrowing and disclosure in this space. For you as a borrower, the message is simple: easy access to credit makes discipline more important, not less.
Responsible personal loan borrowing rests on three ideas:
- Borrow for a need, not an impulse.
- Borrow what you can repay without cutting essentials.
- Know the full cost, not just the EMI.
Now let us turn these ideas into five actionable tips.
Tip 1: Borrow for a Clear, Valuable Purpose
The first step in how to use a personal loan wisely is deciding what the money is for. Ask yourself: will this expense protect my health, income, home or financial stability? If yes, a loan may be justified. If it is mainly for lifestyle upgrades, try saving first.
Smart Ways to Use a Personal Loan
These are the smart ways to use a personal loan, based on common, high-value needs:
Personal Loan for Emergencies
A sudden job gap, urgent travel or a family crisis can drain savings overnight. A personal loan for emergencies gives you quick access to cash without breaking fixed deposits or mutual funds at a bad time. If speed is your priority, see our guide to an instant personal loan for emergency needs, and learn how to get a cash loan online quickly without falling for shortcuts.
Personal Loan for Medical Expenses
Hospital bills in Bangalore can climb fast, especially for surgery, maternity or ICU care. A personal loan for medical expenses is useful when insurance does not cover everything, when you face waiting periods, or when you must pay a deposit upfront. Our article on a personal loan for medical emergency explains how to plan this properly.
Personal Loan for Home Renovation
Repairs such as waterproofing, electrical rewiring or a kitchen refresh can protect your home's value and your family's comfort. A personal loan for home renovation is quick and needs no property papers. Read more in our guide to an online personal loan for home renovation to estimate costs and plan phases.
Personal Loan for Debt Consolidation
This is one of the smartest uses. If you carry several credit card balances at 36% to 42% per year, a personal loan for debt consolidation at a lower rate can cut your interest and replace many due dates with one EMI. The saving only works if you stop adding new card debt afterwards.
Education and Skill Building
A course that raises your earning power can repay itself many times over. Explore personal loan for education: 7 key reasons before you decide.
Business and Self-Employed Needs
Freelancers, consultants and small business owners in Bangalore often face uneven cash flow. If this is you, see our guides on instant personal loan for self-employed applicants and 5 instances when you may need personal loans for your business.
What You Should Avoid Using a Personal Loan For
- Investing in stocks, crypto or speculative schemes (returns are uncertain, EMIs are not).
- Funding a lavish wedding or holiday that you can postpone.
- Paying the down payment on a vehicle or home without a full cost check.
- Lending to friends or relatives.
- Repaying one high-interest loan with another high-interest loan.
Real-world example: Ravi, a software engineer in Whitefield, had ₹1.2 lakh across three credit cards at about 40% annual interest. He took a personal loan of ₹1.2 lakh at 15% for 24 months, cleared all cards and cut his monthly interest outgo by more than half. Because he cancelled two cards, he avoided new debt. That is purpose-driven borrowing.
Soft tip: Not sure which purpose fits your situation? You can browse loan options and see what suits your needs at FixRupee's personal loan page.
Tip 2: Check Eligibility and Borrow Only What You Need
The second lesson in personal loan financial planning is to match the loan amount to your actual need and income. Taking the maximum offered amount is a common mistake.
Understand Personal Loan Eligibility
Personal loan eligibility typically depends on:
- Age: Usually 21 to 60 years for salaried applicants.
- Income: A minimum monthly income, which varies by lender and city. Metro cities such as Bangalore often have higher thresholds.
- Employment: Stable job or business history, often at least six months to a year.
- Credit score: Most lenders prefer 700 or above, and 750 or higher usually earns the best rates.
- Existing obligations: Your fixed obligations to income ratio (FOIR) should usually stay within about 40% to 50%.
If your score is low, do not panic. Read our guides on the minimum CIBIL score for a personal loan and on getting a personal loan with a low credit score to understand your options.
Use the 3-Step Amount Check
Follow this simple method for personal loan budget planning:
- List the exact cost. Get a bill, quote or estimate. Add 5% to 10% for surprises.
- Subtract what you already have. Use savings, insurance payouts or employer reimbursements first.
- Borrow only the gap. Round it up slightly, not by a large margin.
Small needs deserve small loans. If you only need a modest amount for a short time, a smaller ticket may save interest. See options such as a ₹1,000 personal loan or a ₹5,000 personal loan for minor, short-term needs, and our guide to applying for a short-term loan in India if the need is temporary.
Apply the 30% Rule for Affordability
A useful rule of thumb: keep total EMIs, including home, car and personal loans, below roughly 30% to 40% of your monthly take-home pay. If your take-home is ₹70,000, try to keep all EMIs under ₹21,000 to ₹28,000. This leaves room for rent, food, school fees, insurance and savings.
Do Not Forget an Emergency Fund
Before taking a loan for non-urgent goals, ask whether you have three to six months of expenses saved. A loan should not replace your safety net. It should support it.
Tip 3: Compare Personal Loan Offers Before You Apply
Two loans with the same EMI can have very different total costs. Learning how to compare personal loan offers is where many borrowers save the most money.
Compare These Factors
Personal Loan Interest Rates
Personal loan interest rates in India vary widely by lender, profile and credit score. Banks generally charge lower rates for salaried borrowers with strong scores, while NBFCs and digital lenders may charge more but approve faster or accept thinner credit profiles. Rates can range from around the low double digits to above 20% annually. Always check the rate currently offered to you, since it changes with RBI policy, lender pricing and your credit score.
Also check whether the rate is fixed or floating, and whether the loan uses a reducing balance method (preferred) or a flat rate (which costs far more than it appears).
Personal Loan Processing Fees
Personal loan processing fees commonly range from about 0.5% to 3% of the loan amount plus GST, and some lenders charge more. On a ₹5 lakh loan, a 2% fee is ₹10,000 plus GST. Ask whether the fee is deducted from the loan amount, because that reduces what you actually receive.
Personal Loan Prepayment Charges
Personal loan prepayment charges apply when you pay part or all of the loan early. Under RBI directions, regulated lenders cannot levy foreclosure or prepayment charges on floating-rate loans to individual borrowers, but fixed-rate personal loans may still carry charges set by the lender. Check your loan agreement for the exact terms and any lock-in period.
Other Charges to Check
- Late payment penalties
- EMI bounce charges
- Part-payment rules
- Documentation or stamp duty fees
- Insurance add-ons that may be bundled
Use the APR, Not Just the Rate
The annual percentage rate (APR) or the lender's Key Fact Statement (KFS) shows the real cost, including fees. RBI requires regulated lenders to provide a KFS before you sign, so read it carefully.
A Quick Comparison Checklist
- Is the lender a bank or an NBFC registered with the RBI?
- What is the interest rate and method of calculation?
- What is the total processing fee, with GST?
- What are the prepayment and foreclosure terms?
- How long until disbursal?
- How transparent and responsive is customer support?
If you want a shortlist to start with, read our roundup of the best personal loan in India 2026.
Pro tip: Use a soft-enquiry or eligibility checker where possible. Several hard credit enquiries in a short span can lower your score, because lenders see you as credit hungry.
Tip 4: Choose the Right Tenure and Manage Your EMI
Your tenure decides your EMI and your total interest. Good personal loan tenure selection is a balance between a comfortable monthly outgo and a low overall cost.
How Tenure Changes the Cost
Take a ₹3,00,000 loan at 14% reducing balance:
- 12 months: EMI about ₹26,930, total interest about ₹23,200
- 24 months: EMI about ₹14,400, total interest about ₹45,600
- 36 months: EMI about ₹10,250, total interest about ₹69,000
- 60 months: EMI about ₹6,980, total interest about ₹1,18,800
Figures are approximate and for illustration only.
A longer tenure lowers your EMI but raises total interest. A shorter tenure saves interest but needs higher monthly cash flow. The wise choice is the shortest tenure you can pay without stress.
Use a Personal Loan EMI Calculator
A personal loan EMI calculator shows your EMI, total interest and total repayment in seconds. Try different amounts, rates and tenures before applying. Our personal loan EMI calculator complete guide 2026 explains the formula, shows examples and helps you plan.
The standard EMI formula is:
EMI = P × r × (1 + r)^n ÷ ((1 + r)^n − 1)
Where P is principal, r is monthly interest rate (annual rate ÷ 12 ÷ 100) and n is the number of months.
Personal Loan EMI Management Tips
Good personal loan EMI management keeps you out of trouble:
- Set up auto-debit (ECS or NACH) so you never miss a date.
- Align the EMI date with your salary date, ideally two or three days after credit.
- Keep a buffer of at least one EMI in your account.
- Use calendar alerts for the due date.
- Avoid stacking loans. Do not take a second loan unless your total EMIs remain affordable.
- Review your budget monthly and adjust discretionary spending.
Build a Simple Budget
Try a basic 50-30-20 style framework adapted to loan repayment:
- 50% needs: rent, groceries, transport, utilities, school fees
- 30% EMIs and commitments: all loan repayments, insurance premiums
- 20% savings and goals: emergency fund, investments
In a high-cost city like Bangalore, rent can take a large share of income, so adjust the ratios honestly. The aim is to ensure your EMI never forces you to borrow again.
Tip 5: Repay Smartly, Repay Faster and Build Your Credit Score
The final step in how to use an online personal loan wisely is the repayment phase, where discipline pays you back.
Why Timely Repayment Matters
Your payment history is the biggest factor in your credit score. When you improve credit score with timely loan repayment, you unlock lower rates, higher limits and faster approvals on future loans, including home and car loans. On the other hand, a missed EMI can drop your score and attract penalty charges.
How to Repay a Personal Loan Faster
Want to know how to repay a personal loan faster? These tactics form a strong personal loan repayment strategy:
- Make part-payments. Use bonuses, tax refunds or windfalls to reduce principal. Check whether the lender allows part-payment and whether it reduces tenure or EMI. Prefer reducing tenure, since it saves more interest.
- Increase your EMI slightly. Even a 10% rise in EMI can cut months from the loan.
- Prepay in the early years. Interest is front-loaded, so early prepayments save the most.
- Pay biweekly equivalents. If your lender permits, extra payments through the year work like a thirteenth EMI.
- Refinance or balance transfer. If your credit score has improved and rates have dropped, a balance transfer to a cheaper lender can lower interest. Compare the new processing fee before moving.
- Avoid new debt until the existing loan reduces.
Example: On a ₹3,00,000 loan at 14% for 36 months, paying one extra EMI of about ₹10,250 each year could save several thousand rupees in interest and shorten your term by a few months.
Personal Loan Repayment Tips for Tough Months
If you face job loss or a medical crisis:
- Talk to your lender early. Many offer restructuring, a short moratorium or tenure extension.
- Never ignore calls or notices. Silence makes things worse.
- Prioritise high-interest debt while paying minimums on others.
- Cut non-essentials temporarily.
- Do not borrow from illegal or unregulated apps to repay your loan.
Tips for Managing Loan Debt Over Time
These tips for managing loan debt support long-term health:
- Track all loans in one sheet with rate, EMI, due date and balance.
- Use the debt avalanche method (pay highest-interest first) to save money.
- Use the debt snowball method (pay smallest balance first) if you need motivation.
- Check your credit report at least once a year for errors, and dispute mistakes promptly.
- Close the loan formally and collect a no-dues certificate and updated credit report.
Mistakes to Avoid When Taking a Personal Loan
Knowing the mistakes to avoid when taking a personal loan can save you lakhs over time:
- Borrowing the maximum approved amount when you need less.
- Ignoring the total cost and focusing only on the EMI.
- Applying to many lenders at once, which creates multiple hard enquiries.
- Skipping the fine print on charges, penalties and add-on insurance.
- Choosing too long a tenure just for a smaller EMI.
- Using the loan for speculation or non-essential spending.
- Missing EMIs, which damages your score.
- Trusting unverified apps that ask for upfront fees or excessive phone permissions.
- Not checking RBI registration of the lender or its lending partners.
- Skipping a repayment plan before signing.
How to Apply for an Online Personal Loan: Step-by-Step
Here is a simple guide to a smooth online loan application:
- Define your need and amount using the 3-step check above.
- Check your credit score and fix errors if any.
- Calculate your EMI with a personal loan EMI calculator.
- Compare lenders on rate, fees, tenure and prepayment terms.
- Keep documents ready: Aadhaar, PAN, recent salary slips or income proof, and 3 to 6 months of bank statements.
- Fill in the online application with accurate details.
- Complete e-KYC and verification.
- Review the Key Fact Statement and loan agreement carefully.
- Accept the offer and set up auto-debit.
- Receive funds and start your repayment plan.
For tips on faster verification, read our guide on instant cash loan approval and verification tips.
Personal Loan Tips for Bangalore Borrowers
Bangalore has a distinct financial profile, with a large base of IT professionals, startup employees, freelancers and gig workers. A few local insights:
- Salary variability: Startup bonuses and ESOP-linked pay can be irregular. Base your EMI on fixed pay only.
- High living costs: Rent deposits and commute costs can strain monthly budgets, so keep your EMI-to-income ratio conservative.
- Self-employed and freelance borrowers: Keep income tax returns and GST records organised, since lenders rely on them.
- Digital comfort: Bangalore borrowers often use fintech platforms. Always verify that the lender is RBI-registered and that the loan agreement is clear.
Why FixRupee Is Important for This Journey
Choosing the right lender is half the battle in personal loan management, and that is where a trusted platform helps. FixRupee is built around the idea that borrowers deserve clarity before commitment. Here is why it matters for the five tips in this guide:
- Comparison in one place: Instead of visiting several lender sites, you can review personal loan options and understand your choices through FixRupee's personal loan page.
- Education first: The platform's blog cluster, which covers eligibility, CIBIL scores, EMIs, medical needs, renovation and short-term loans, helps you make informed decisions before you apply.
- Support across profiles: Salaried, self-employed and low-score applicants each find relevant guidance, instead of generic advice.
- Digital convenience: A simple online process saves time when you need funds urgently.
- Focus on responsible borrowing: Content and tools are designed to help you borrow what you need and repay on time.
In short, FixRupee supports every stage of the loan journey, from learning to comparing to applying, so you are not guessing along the way. As with any loan, always read the final terms offered by the lender before accepting.
5 Smart Tips at a Glance
- Borrow with purpose: emergencies, medical bills, renovation, debt consolidation and education are valid reasons.
- Check eligibility and amount: borrow only the gap, and keep EMIs within 30% to 40% of take-home pay.
- Compare offers: look at interest rates, processing fees, prepayment terms and total cost.
- Pick the right tenure: choose the shortest one you can afford and manage EMIs with auto-debit.
- Repay smartly: pay on time, make part-payments and use repayment to build your credit score.
Frequently Asked Questions (FAQs)
1. How do I use an online personal loan wisely?
To use an online personal loan wisely, borrow only for a clear need such as a medical bill, home repair or debt consolidation. Check your eligibility, calculate your EMI, compare interest rates and fees across lenders, choose a comfortable tenure and repay on time. Keep your total EMIs within roughly 30% to 40% of your monthly take-home pay.
2. What is the best use of a personal loan?
The best uses are those that protect your finances or improve your future: emergency expenses, medical treatment, essential home renovation, education and consolidating high-interest credit card debt. Avoid using it for speculation, luxury spending or lending to others.
3. How can I repay a personal loan faster?
You can repay faster by making part-payments, raising your EMI slightly, using bonuses or windfalls to reduce principal and choosing a shorter tenure from the start. Check your loan agreement for prepayment rules and charges before you pay extra.
4. Does repaying a personal loan improve my credit score?
Yes. Timely EMI payments build a positive repayment history, which is a major factor in your credit score. A better score can help you get lower interest rates and higher loan amounts later. Missed or delayed EMIs can lower your score.
5. What charges should I check before taking a personal loan?
Check the interest rate and calculation method, processing fee plus GST, late payment penalty, EMI bounce charges, part-payment rules and prepayment or foreclosure charges. Also read the lender's Key Fact Statement, which shows the total cost of the loan.
6. Can I get a personal loan with a low credit score?
It is possible, but you may face higher interest rates, lower amounts or need a co-applicant. Some lenders focus more on income and stability. Improving your score before applying can reduce your cost. Read our guide on personal loans with a low credit score for more detail.
Conclusion: Borrow Smart, Repay Smarter
Knowing how to use an online personal loan wisely can turn a stressful moment into a manageable one. Remember the five steps: borrow with a clear purpose, match the amount to your need, compare offers beyond the EMI, choose a tenure that fits your budget, and repay with discipline to build your credit score. A personal loan used well can fund an emergency, protect your health, upgrade your home or lower your interest burden. Used carelessly, it can trap you in a cycle of debt.
Before you commit, run the numbers on an EMI calculator, read the fine print and check your repayment capacity honestly. When you are ready, take the next step with confidence.
Ready to apply the smart way? Start your application today at FixRupee Loan Onboarding and take control of your finances with a personal loan that fits your plan.